

That Sinking Feeling When the Estimate Lands
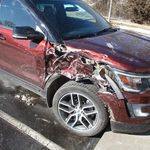
The crash is over. Nobody’s hurt, thank goodness. You’ve traded insurance info, snapped a few photos, and maybe even made it home.
Then it hits you. You still have to pay your deductible.
Maybe it’s $500. Maybe it’s $1,000. Either way, it’s money you didn’t plan to spend this month. And it’s showing up right next to a car you can’t drive, a rental you might need, and a pile of phone calls you don’t want to make.
Sound familiar? You’re not alone. Most insured drivers feel this exact squeeze after an accident. The good news is you have more options than you think.
In this guide, you’ll learn how your deductible really works in collision repair, when you might not owe it at all, how to get some of it back, and which “deals” to steer clear of. We’ll also share what we’ve learned from years of fixing cars right here in Andover.
Your Deductible, Explained Without the Insurance-Speak
Here’s the thing. A deductible is just your share of the repair bill. Your insurance company pays the rest.
So if your repair costs $4,200 and your deductible is $500, you pay $500. Your insurer covers $3,700. Simple enough.
But here’s what most people miss. You usually pay the deductible to the repair shop, not to your insurance company. The insurer sends the shop its share, and you pay yours when you pick up your car.
Why the Number Never Changes
Your deductible stays the same whether the repair costs $1,500 or $15,000. That’s actually good news if the damage is serious. A big repair doesn’t mean a bigger deductible.
It’s a tougher deal when the damage is small, though. If a scrape costs $700 to fix and your deductible is $500, filing a claim only saves you $200. In that case, some drivers choose to pay out of pocket. That way, a small claim doesn’t show up on their record.
Collision vs. Comprehensive: Two Different Deductibles
This one trips people up all the time. Your policy probably has two deductibles.
Collision coverage handles crashes with another car or an object, like a pole or a guardrail. Comprehensive coverage handles things that aren’t crashes. Think hail, a deer, a falling tree branch, or a broken windshield.
Why does this matter? Lots of Kansas drivers carry a lower comprehensive deductible. So after a spring hailstorm, your out-of-pocket cost might be smaller than you’d expect. Check your policy before you panic.
When Someone Else Should Be Paying
Look, if the other driver caused the crash, you may not owe a deductible at all.
Kansas is an “at-fault” state for property damage. That means the driver who caused the accident is responsible for the damage. Their liability insurance should pay for your collision repair.
You have two paths here. You can file with the other driver’s insurance company directly. Or you can file with your own insurer and let them chase the other company for the money.
Path One: File With Their Insurance
Going straight to the at-fault driver’s insurer means no deductible from you. That’s the upside.
The downside? It can be slower. Their company has to accept blame first. If fault is unclear or they drag their feet, you might wait days or even weeks.
Path Two: File With Yours and Get It Back
Filing with your own insurance is often faster. You pay your deductible up front, and your car gets fixed.
Then your insurer goes after the other driver’s company. This process is called subrogation. If they win, you can often get some or all of your deductible back. It can take a few months, but it’s your money. Call your agent and ask about it if you haven’t heard anything.
This doesn’t work if fault is split or if the other driver has no insurance. In those cases, you may only get part of it back, or nothing.
Comparing Your Options at a Glance
Here’s a quick look at how the most common situations shake out for your wallet.
| Situation | Who Pays for Repairs | Do You Pay a Deductible? | Speed | Good to Know |
| Other driver at fault, file with their insurer | Their liability coverage | No | Can be slower | Depends on their company accepting fault |
| Other driver at fault, file with your insurer | Your collision coverage first | Yes, up front | Usually faster | You may get the deductible back later through subrogation |
| You’re at fault | Your collision coverage | Yes | Normal | Ask about payment options at the shop |
| Hail, deer, or falling object | Your comprehensive coverage | Yes, often lower | Normal | Paintless dent repair may keep costs down |
| Small damage under or near your deductible | You | Pay out of pocket | Fast | Keeps a minor claim off your record |
| Other driver uninsured | Your coverage, if you carry it | Usually yes | Varies | Check your policy for uninsured motorist coverage |
The “We’ll Cover Your Deductible” Trap
It’s frustrating to pay a deductible. So when a shop offers to “eat” it or “make it disappear,” it can feel like a lifesaver.
But here’s what matters. If a shop waives your deductible and still bills your insurer the full amount, that can be insurance fraud. In many states, it puts you at risk too, not just the shop.
And think about it. If a shop is giving up $500 to $1,000 on your job, where does that money come from? Too often, it comes from the repair itself. Cheaper parts. Skipped steps. A quick paint job hiding damage underneath.
Honest Ways to Lower Your Cost
There are real ways to save money, though. A good shop will walk you through them.
Ask if paintless dent repair (PDR) can handle any of your dents. It’s often cheaper and keeps your factory paint. Ask about discounts, too. For example, Collision Center of Andover takes $100 off the deductible for military members, which matters to a lot of families near McConnell AFB.
And always ask for a clear, written estimate before work begins. You should know exactly what’s being fixed and why.
Hidden Damage: The Surprise Nobody Wants
You might feel relieved when the first estimate comes in lower than you feared. Then, two days later, the shop calls. They found more damage.
Ugh. It happens more than you’d think.
Modern cars hide a lot behind the bumper. Sensors, brackets, and crush zones can bend without you ever seeing it. A shop can’t see all of that until they take the car apart.
Why a “Supplement” Isn’t a Scam
When a shop finds hidden damage, they send a “supplement” to your insurer. That’s just an updated estimate.
Here’s the good part. Your deductible doesn’t go up. The insurer covers the extra repair cost. Your share stays the same.
What you want is a shop that tells you upfront that this might happen. No surprises later. That’s a big part of why straight talk matters so much in collision repair.
You Get to Pick the Shop (Yes, Really)
Your insurance company might suggest a shop from its network. That can feel like an order. It isn’t.
In Kansas, drivers generally have the right to choose where their car gets fixed. Your insurer can recommend a shop, but the choice is yours.
Questions Worth Asking Before You Hand Over Your Keys
So how do you pick? Start with training. I-CAR Gold Class is one of the top standards in the industry, and only a small share of shops earn it.
Next, ask about the guarantee. Does the shop back its work for as long as you own the car? Or just for a year?
Finally, ask who you’ll talk to. Is there a real person who knows your car? Or will you end up on hold with a call center two states away?
At Collision Center of Andover, the answer to that last one is easy. The shop has been locally owned since 2006, and the owner is an Andover native. When you call, you’re talking to your neighbors.
What Our Shop Floor Has Taught Us About Deductibles
We’ve fixed thousands of cars over the years. Some lessons only come from doing the work.
First, most people don’t know they might get their deductible back. We’ve seen customers forget about it completely. A five-minute call to your agent a month after the repair can put real money back in your pocket.
Second, the cheapest estimate often isn’t the cheapest repair. A low bid that leaves out steps tends to come back. Then you’re dealing with the hassle all over again, maybe without a warranty.
Third, getting a rental lined up early takes a lot of stress out of the process. Check if your policy includes rental coverage. If the other driver is at fault, their insurer should cover a rental too.
And finally? People feel better when they understand what’s happening. That’s why we explain the repair before we start. You deserve to know where your money goes.
Frequently Asked Questions
Do I have to pay my deductible before collision repair starts?
Usually not. Most shops collect your deductible when you pick up your finished car. Your insurer pays its share directly to the shop. Ask your shop about their payment timing so there are no surprises at pickup.
Can I get my deductible back if the other driver was at fault?
Often, yes. If you filed with your own insurer, they can recover costs from the at-fault driver’s company through subrogation. When they succeed, you typically get some or all of your deductible refunded. It can take a few months, so follow up with your agent.
Does my deductible go up if the shop finds more damage?
No. Your deductible is a fixed amount set by your policy. If the shop finds hidden damage, the insurer pays the added cost through a supplement. Your share stays the same.
Is it worth filing a claim for minor damage?
It depends on the numbers. If the repair costs only a little more than your deductible, paying out of pocket may make more sense. That keeps a small claim off your record. Get a free estimate first so you can compare.
Back on the Road Without the Headache
An accident throws a lot at you at once. The deductible is just one piece, but it’s the piece that hits your wallet hardest.
Here’s the takeaway. Know which coverage applies, find out who’s at fault, and ask about getting your deductible back. Skip any shop that offers to “make it disappear.” And remember, you get to choose who fixes your car.
When you’re ready, Collision Center of Andover is here to help. We work with every insurance company, help arrange your rental, and back our workmanship with a lifetime guarantee. Fixed right. Backed for life. By your neighbors.
Get your free estimate at Collision Center of Andover, call (316) 733-9310, or stop by 948 N. Andover Rd, just off I-35.